How incorporated owners 40+ use an Individual Pension Plan to save more than their RRSP allows — with Greg Rozdeba and IPP specialist Fraser Lang of GBL.
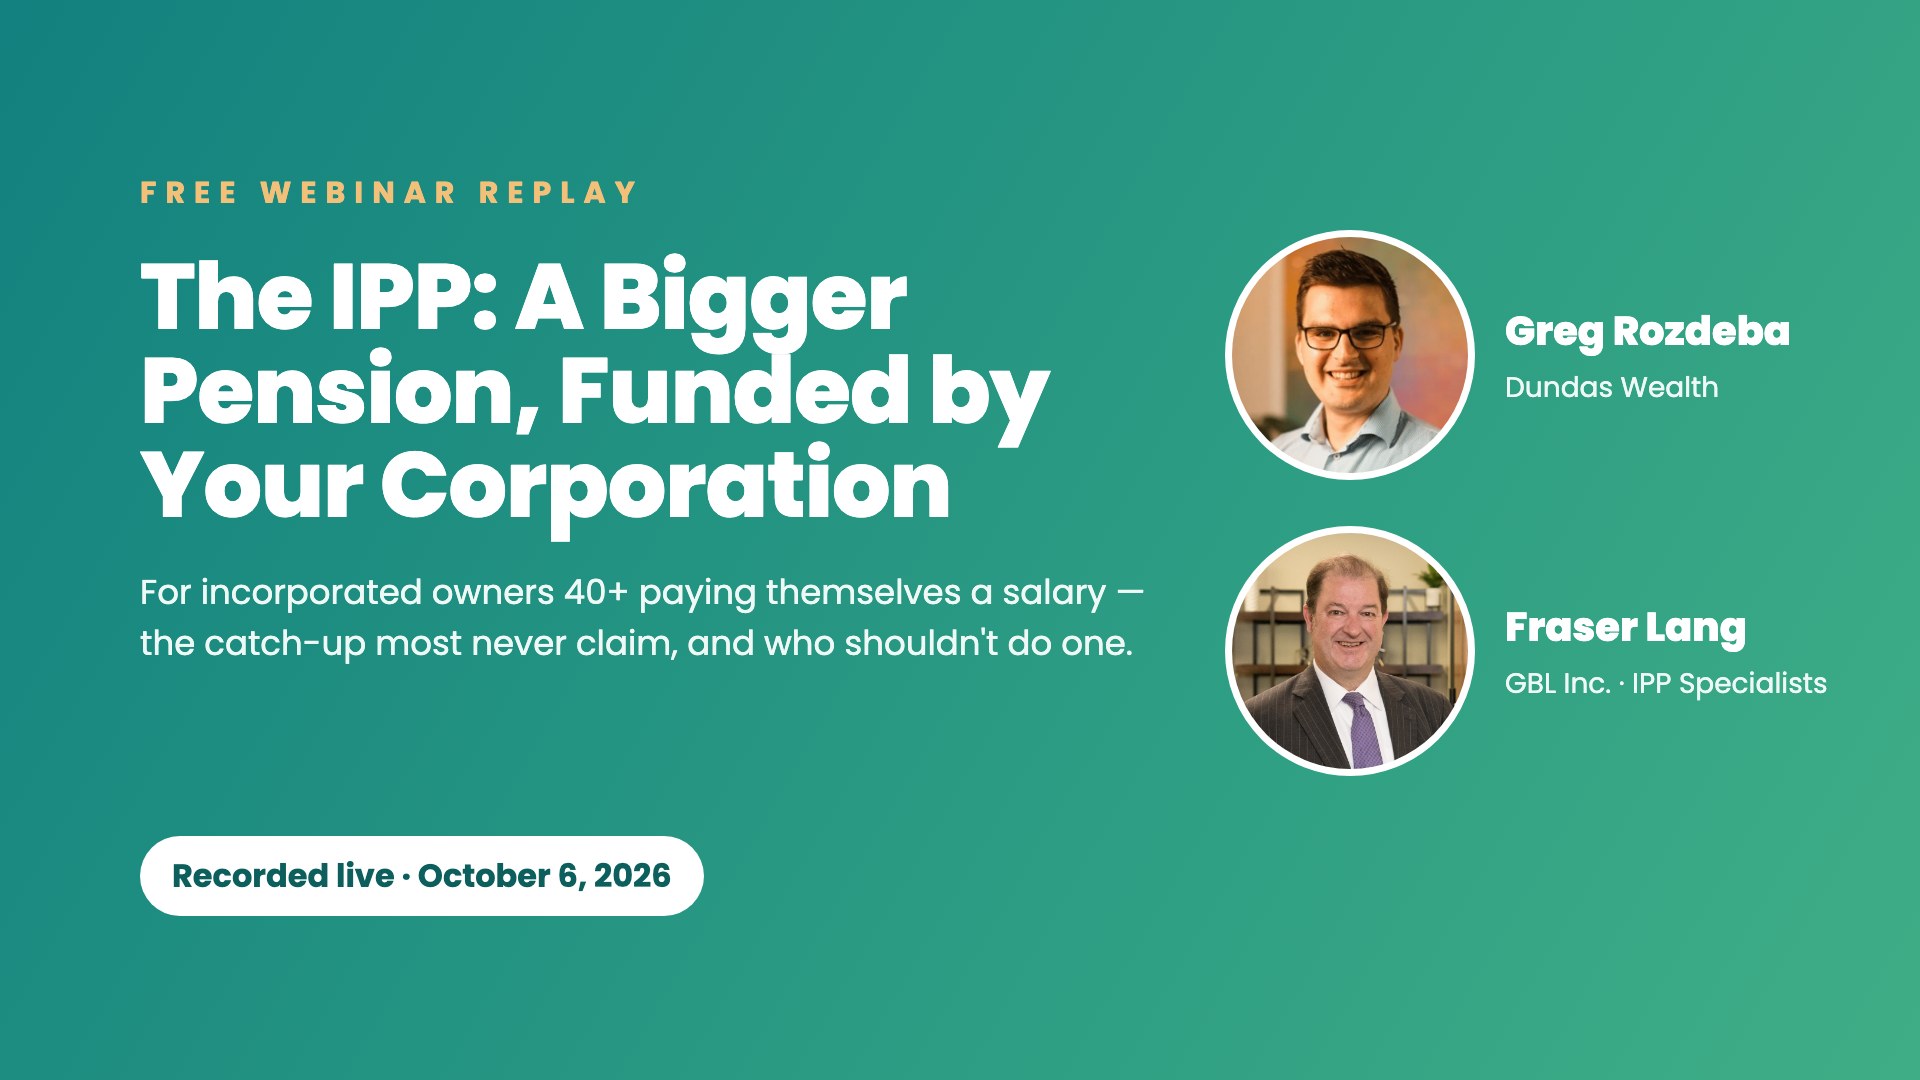
30 minutes with Greg Rozdeba · No obligation · Free
IPP Decision Kit — book by Friday, October 9 at 11:59 PM ET and it comes with your session: the IPP Readiness Checklist, the $50K Trap replay, and an introduction to an actuary if the fit is there. The session itself stays free after Friday.
Everyone gets the same flat RRSP limit, whether retirement is 35 years away or five. Why that quietly penalizes owners over 40, and the age where the math flips.
A defined-benefit pension your corporation sets up for you. It funds the contributions, deducts them (plus setup, actuarial and investment fees), and growth stays tax-sheltered inside the plan.
Past-service funding can recognize salary years back to when you incorporated, and terminal funding adds more at retirement. Illustrative — varies by age, salary history and province.
The setup and actuarial costs, the lock-in, and the T4-salary requirement. For the right owner an IPP is excellent; for everyone else it’s overkill.
Thirty minutes with Greg Rozdeba — your age, T4 salary history and incorporation year, and a straight read on whether an IPP is worth pricing. If the honest answer is “stick with your RRSP,” you’ll hear it in the first ten minutes. If the fit is there, he introduces you to an actuary to price the plan, or to a tax partner — a CPA or tax planner — if your salary mix comes first. No product, no pitch.
Book by Friday, October 9 at 11:59 PM ET for the
IPP Decision Kit — a real deadline, not a timer.
The session stays free —
book the next open slot.
Educational only. Dundas Wealth and GBL Inc. do not provide tax, legal or investment advice in this recording, and watching it does not create an advisory relationship. IPP figures are illustrative and vary by age, salary history and province; only an actuarial valuation sets the real numbers. Growth inside an IPP is tax-sheltered, not tax-free: pension income is taxable when paid.