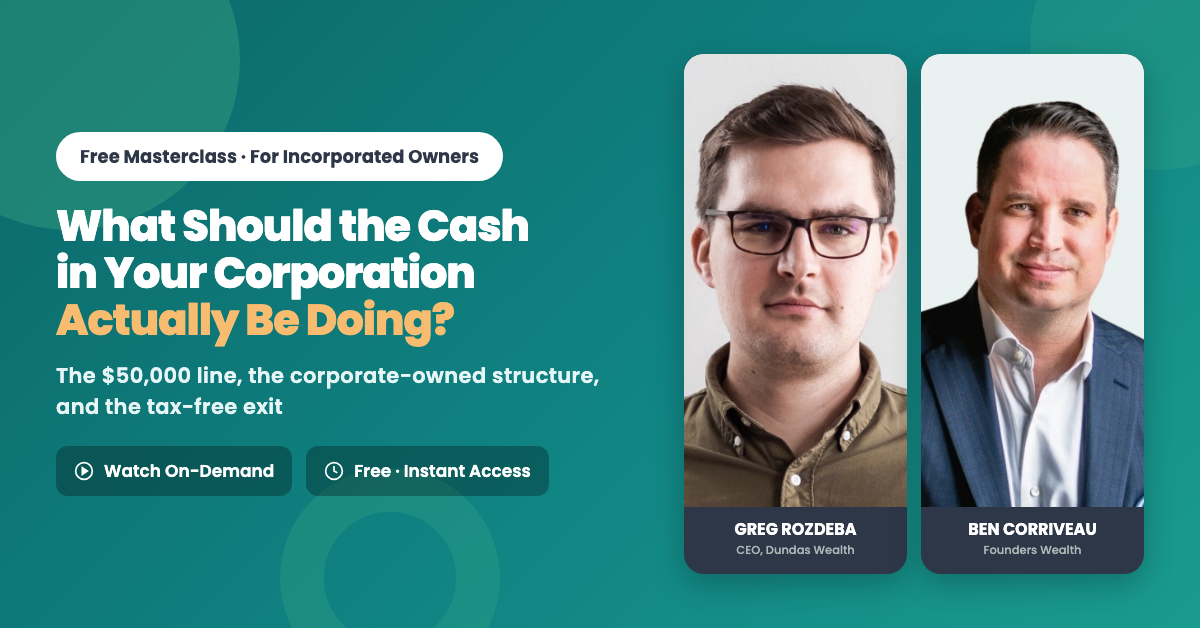
The $50,000 passive-income line. The corporate-owned structure most owners never see. The way money leaves the corporation without tax. Greg Rozdeba and Ben Corriveau walk through it with real owner cases.
What you’ll be watching
What You'll Learn
Recorded live with a room of incorporated owners. Ben walks through the structure and the cases. Greg ties it together and runs the Q&A.
Above $50,000 of passive income a year, your small business deduction starts to shrink: $5 for every $1 over, gone at $150,000. Cash in a GIC triggers it quietly.
How retained earnings stay invested while also funding a tax-sheltered asset the corporation owns, with no net cash leaving the company.
How the CDA moves corporate wealth to your family without tax on the way out, and the owner cases Greg and Ben walked through live.
The Hidden Problem
Most owners leave corporate cash in a GIC or a brokerage account because it feels safe. It isn't free. The passive income it earns can grind your small business rate, the money is taxed again on the way out to you, and at death it can be taxed twice. The masterclass shows where each of those costs hides.
Watch Now — FreeCash parked in the corporation earns passive income. Past $50,000 a year, that income starts grinding your small business deduction — and most owners find out from their accountant after it has already happened.
Owners pay for protection personally with after-tax dollars, while the corporation sits on cash taxed at the small business rate. Same coverage, funded from the wrong pocket — and none of the corporate planning benefits.
Money that goes into a corporation has to come out someday — as a dividend to you, or through your estate. Without a plan, every route is taxed. The Capital Dividend Account is the one that isn't, and most owners have never had it explained.
Your Hosts
Co-founder of Dundas Wealth, specializing in coordinated tax, wealth, and succession planning for incorporated Canadian business owners. Greg moderates, ties the tax, insurance, and exit layers together, and runs the Q&A.
Partner at Founders Wealth (Toronto), advising Canadian business owners on corporate insurance, corporate investment structures, and intergenerational wealth transfer. Ben walks through the corporate-owned structure, the $50,000 line, and the Capital Dividend Account with real owner cases.
The Corporate-Owned Structure
The masterclass walks through how real incorporated owners set it up — what stays invested, what the corporation owns, and how the money eventually leaves without the tax bill.
Retained earnings keep working inside the corporation instead of being pulled out and taxed to fund protection personally.
A corporate-owned policy builds cash value on the balance sheet that the corporation controls — and can borrow against — while the death benefit protects the business and the family.
The Capital Dividend Account moves money from the corporation to your family without tax — the planning tool most owners are never shown, explained with the cases from the live session.
Client Stories
"Coming from the financial space I needed advisors I can trust. Independent brokers have access to the most complete suite of products but I also wanted someone who can deal with more complex tax planning scenarios. Dundas has it all."
"Working with the team was a great experience. Transparent and genuine. They spent the time to understand my needs, put them first and then worked to provide options that were best suitable. I've recommended my family and friends."
"Fantastic experience with Dundas. The service provided was timely and saved me a significant amount on insurance. The whole process was seamless and professional. Highly recommend to any business owner."


Instant access — watch the full masterclass on demand
Free. Full replay. No pitch — just what the cash in your corporation should be doing.